


Lenders
Lenders lend money to borrowers in the form of a mortgage (or charge), to fund the purchase of a property. This is subject to:
-
The borrower's affordability
-
The property meeting the lender's lending policy
Lenders require the advice of other stakeholders in the process to establish the value of the property and ensure that the loan to value meets their requirements.
Following the implementation of the protocol, lenders will have the opportunity to collaborate with other stakeholders to ensure an efficient customer journey.
Process flow to exchange of contracts
When recommended practice is followed, these are the key stages in a property transaction involving Lenders and the main activities they are involved in
Decision in principle
-
Borrower ID
-
VISA if applicable,
-
Income, credit reference
-
AML due diligence
-
Mortgage Decision in Principle
-
Proof of funds and Buyer ID
-
Review Material Information on affordable property
Pre-Viewing
Mortgage decision in principle
-
Mortgage application
-
Contract pack
-
Valuation
-
Survey (where advised)
-
Due diligence
-
Enquiry of specifics relevant to the buyer and their lender
Rules and Regulations
The following rules and regulations apply to lenders
-
In the UK, lenders need to abide by the Financial Conduct Authority (FCA) code of conduct, in particular the Mortgages and Home Finance: Code of Business (MCOB), including the Consumer Duty to prevent foreseeable harm. Lenders are also subject to legally binding decisions of the Financial Ombudsman Service if the borrower complains.
-
The Consumer Protection from Unfair Trading Regulations 2008 (Consumer Protection Regulations, CPR) which is updated by the Digital Markets, Competition and Consumers Act 2024 identifies what information should be revealed to the borrower during the process.
-
Lenders must adhere to the Money Laundering Regulations 2017 and be aware of the Proceeds of Crime Act 2002, which is the main money laundering legislation covering offences in the UK.

Material Information and EPCs
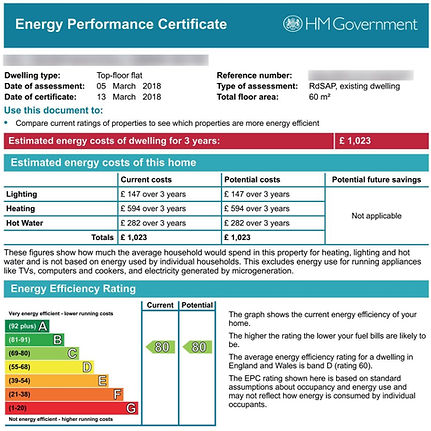
Material Information (MI) means the information relevant to the property which would impact the average consumer’s ability to make an informed transactional decision.
This covers the legal and physical aspects of the property, along with the affordability of the financial aspects.
This will include things like:
-
Size of the property
-
Any restrictions on the property
-
The tenure of the property (leasehold, freehold, commonhold)
What data does a lender need?
A lender would benefit from a range of data to support their service, including
Personal details
-
Anti-Money Laundering (AML) verification
-
Any outstanding credit and debt
-
Bank statements
-
Borrower credit score and credit references
-
Borrower ID and any necessary visas
-
Employment and self-employment details
-
Evidence of income
-
Full property portfolio (for Buy to Let transactions)
Property details
-
Council tax
-
Energy Performance Certificate (EPC)
-
Property risk information
-
Property type
-
Size of property (m²)
-
Tenure

Data sources
An Estate Agent can obtain data from a variety of sources, including

Asking the borrower for the data

Mortgage intermediary supplies data on application or decision in principle
Gathering information direct from relevant authority

Verifying* the Material Information in existing Property Logbook

Receiving verified* Material Information and borrower data, either directly or shared by others in the process
* Authenticating the origin of the data, allows the lender to establish whether the information is verified by the relevant data authority.
Sharing data
The following information obtained by the lender could then be shared with other stakeholders for their benefit
Digital verification certificates will speed up the verification under Anti-Money Laundering requirements for estate agents, conveyancing lawyer and mortgage intermediaries.

The data in the property description, searches, title and seller information is also used by conveyancing lawyers, surveyors, valuers, mortgage intermediaries, estate agents and domestic energy assessors to provide their services.
Benefits and opportunities in collaborating
to share data
Sharing data early and throughout the buying and selling process offers conveyancing lawyers a range of benefits, including
Greater transparency
-
The borrower’s information allows lenders and providers to identify the borrower’s affordability and obtain a mortgage in principle. This helps the borrower only look at affordable properties, preventing time wasting.
-
Furthermore, the details provided can provide more assurance of successful lifetime mortgage application or port/move proposal.
-
For lenders, Material Information identifies whether the property meets their lending policy requirements.
Faster
certainty
-
Upfront information allows mortgage applications for properties uncompliant with the lending policy to be rejected.
-
Relevant material data allows lenders to identify early whether they will lend on a property of that type.
-
Incorporating digital survey data and Material Information into the valuation will reduce post valuation queries.
Better
outcomes
-
Greater protection against fraud and money laundering.
-
Less waste on declined applications and transactions falling through.
-
Improved consumer understanding allowing them to find the right lender product for them and the property.
-
More fulfilling job roles.
-
Improved conversion and completion rates for lenders.